Guide 03
How to buy a pre-foreclosure home
3 min read · updated October 29, 2026

A pre-foreclosure is bought from its owner, not from a court. That makes it slower and more personal than a foreclosure sale, and it rewards whoever gets there early and treats the owner well. 3,191 new cases were first published here in the last 30 days.
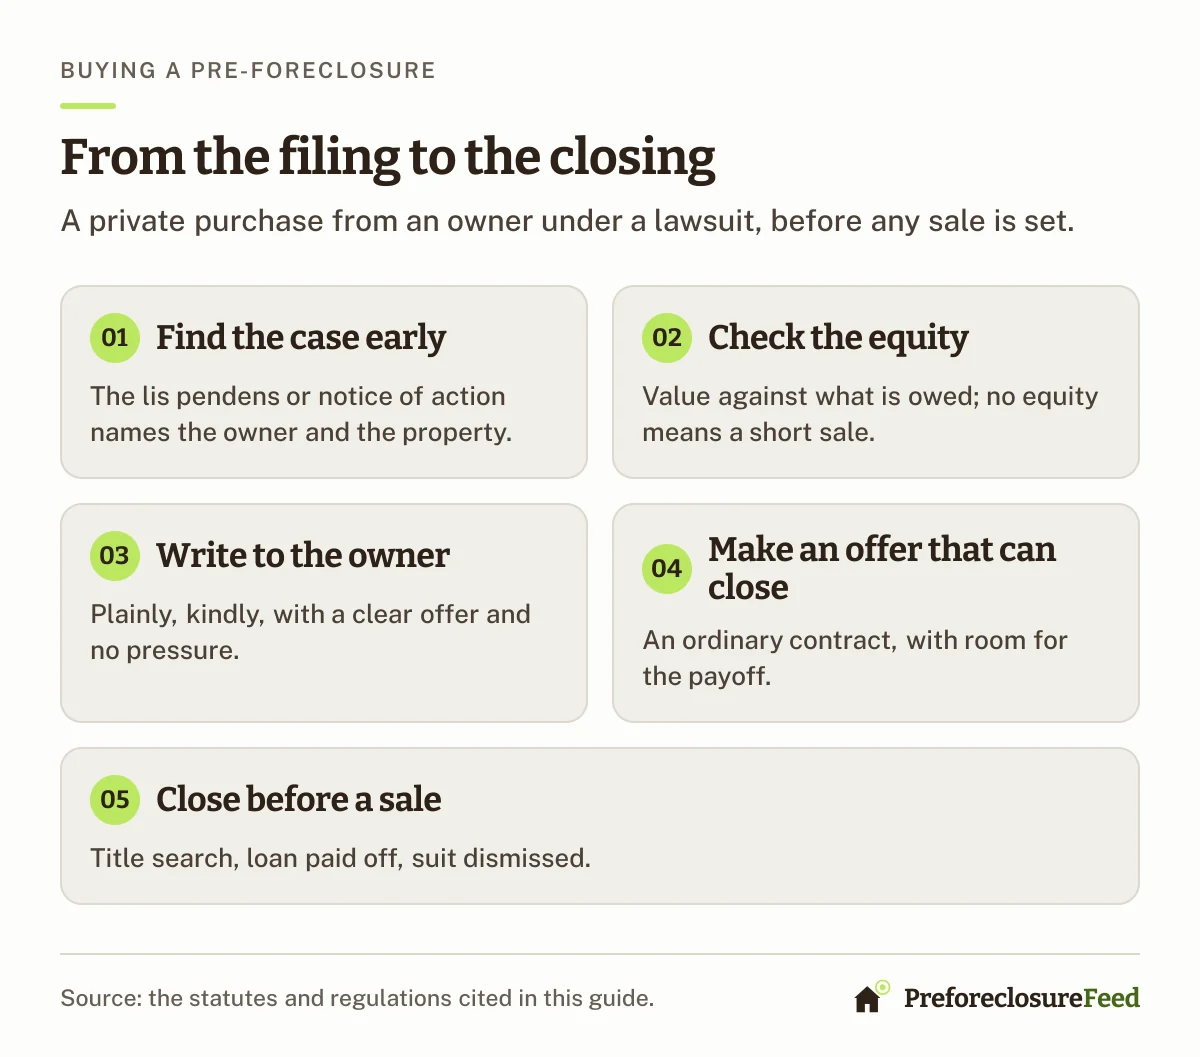
1. Find the case early
To buy a pre-foreclosure, start from the public filing: the lis pendens or the notice of action names the owner, the property and the lender months before any sale can be set.
The earlier you see a case, the more choices the owner still has, and the fewer other buyers have written to them. In Florida a notice of action gives the owner 30 days from its first publication to answer the suit [1], and no sale can be set until a final judgment after that [2]. A daily alert for the counties you work turns that window into a routine.
2. Check the property and the equity
Look the parcel up in the county property appraiser's records, by parcel ID, address or legal description, to see the owner of record, the assessed value and the tax status. Estimate what the home would sell for. Then estimate what is owed: the original loan on the record, interest and arrears since the default, fees, and any junior liens or association dues.
Equity decides the deal. With equity, the owner can sell to you, pay off the loan and walk away with money. Without it, the lender has to agree to take less, a short sale, and its approval takes time.
3. Reach the owner, plainly and kindly
Write to the mailing address on the record; many owners in pre-foreclosure have moved, which is why they were served by publication. Say who you are, that you saw the court filing, and what you can offer: a quick sale, a fair price, help with moving. Never pressure, never promise to stop the foreclosure, and never ask for money or the deed up front.
Owners can still reinstate, refinance or agree loss mitigation with the servicer; say so. A complete loss mitigation application received more than 37 days before a sale stops the servicer from moving for judgment while it is reviewed [3]. An owner who keeps the home is a good outcome too. Many states also regulate buyers and consultants who deal with homeowners in foreclosure; know the rules where you work.
Cases naming the unknown heirs of a deceased owner are a different conversation: the heirs decide together, sometimes through a probate court, and may need time.
4. Make an offer that can close
Put the price, the closing date and the contingencies in an ordinary purchase contract. Leave room for the payoff: ask the owner to request a payoff statement from the servicer, so both of you know what has to be paid at closing. If the price is below the payoff, the owner's lender must approve a short sale before you can close.
5. Close before a sale is set
Order a title search and title insurance as for any purchase. The search shows the lis pendens, the mortgage being foreclosed, and any other liens to be paid or released. At closing the loan is paid off from the proceeds, the lender dismisses the suit, and the lis pendens is released. Until the clerk files a certificate of sale, an owner who pays the debt can still stop a Florida foreclosure [4], but a buyer who waits for that last moment is gambling the owner's equity, and their own deal.
Sources
- [1]Fla. Stat. § 49.09 — Florida Legislature“In foreclosure proceedings, the notice of action shall require the defendant to file written defenses with the clerk of the court and to serve a copy within 30 days after the first publication of the notice”
- [2]Fla. Stat. § 45.031(1)(a) — Florida Legislature“the court shall direct the clerk to sell the property at public sale on a specified day that shall be not less than 20 days or more than 35 days after the date thereof”
- [3]12 C.F.R. § 1024.41(g) (Regulation X) — Consumer Financial Protection Bureau“If a borrower submits a complete loss mitigation application after a servicer has made the first notice or filing required by applicable law for any judicial or non-judicial foreclosure process but more than 37 days before a foreclosure sale, a servicer shall not move for foreclosure judgment or order of sale, or conduct a foreclosure sale”
- [4]Fla. Stat. § 45.0315 — Florida Legislature“At any time before the later of the filing of a certificate of sale by the clerk of the court or the time specified in the judgment, order, or decree of foreclosure, the mortgagor or the holder of any subordinate interest may cure the mortgagor's indebtedness and prevent a foreclosure sale”
Questions
How do you buy a house in pre-foreclosure?
Find the case early, check the property and what is likely owed, contact the owner with a clear offer, sign an ordinary purchase contract, run a title search, and close before a sale is set, with the mortgage paid off from the proceeds. If the owner owes more than the price, the lender has to approve the sale as a short sale.
Can you buy a pre-foreclosure below market value?
Sometimes, because the owner wants speed and certainty more than the last dollar. But the owner is not obliged to discount, and a buyer who pays too little leaves the owner nothing to settle the debt with. The deals that close are the ones that work for both sides.
How do I find pre-foreclosure homes?
From the public filings: the lis pendens recorded in the county's official records and, in Florida, the notices of action published to serve owners who could not be served in person. PreforeclosureSearch reads those notices every day and turns each case into one record, with the owners, their mailing addresses, the property and the lender.
Do you need cash to buy a pre-foreclosure?
Not necessarily. A pre-foreclosure is bought with an ordinary contract, so financing can work if the timeline allows it. Cash helps when the owner needs to close quickly, before the case reaches a judgment.
Where next
- Pre-foreclosures by stateEvery state and county we cover, with new filings this week.
- Search every caseBy county, owner, lender, case number, street or ZIP code.
- Pre-foreclosure guidesWhat a pre-foreclosure is, how it differs from a foreclosure, Florida's lis pendens, and how to buy one.
- Pre-foreclosure glossaryLis pendens, notice of action, unknown heirs, reinstatement, deed in lieu: every term a filing uses.
General information about foreclosure law across the states, not legal advice. Foreclosure law differs from state to state and statutes change; confirm a case's docket with the clerk of court, and the rules that apply to you, before you act.